
Written by Bertrand Théaud, Statrys Founder
20+ years in Asia as a corporate lawyer, investor, and fintech founder. I've sat on both sides of the table and seen the same avoidable mistakes hit founders again and again. The reviews and articles I write are for founders who'd rather skip the mistakes.
Key Takeaways
An IBAN (International Bank Account Number) identifies a specific bank account for cross-border transfers. It combines a two-letter country code, two check digits, and up to 30 characters for the account number.
A correctly formatted IBAN is not proof the payment will land in the right account. For transfers outside the SEPA zone, the check digits catch typos, not wrong account numbers, so validate the account holder's name yourself, not just the string of characters.
Around 90 countries use the IBAN standard, mainly in Europe, the Middle East, and parts of Africa. The US, Canada, Australia, and most of Asia don't use IBANs domestically, but their banks still receive IBAN-format payments from abroad.
Sending a payment with the wrong format, or omitting the IBAN where it's required, routinely adds 3-5 business days and USD 15-40 in correction fees.
IBANs are essential for payments to and from countries that use this international banking standard. Without the correct IBAN, your payment could be delayed, rejected, or hit with additional fees. These complications can strain vendor relationships and disrupt cash flow.
This guide will show you exactly what an IBAN is, when you need IBANs, how to find the right numbers, and how to use them confidently for international payments.
What is an IBAN?
An IBAN (International Bank Account Number) is a standardised code that identifies a specific bank account across borders. It was developed by the European Committee for Banking Standards to cut down on the payment errors and delays that came from every country using its own account-numbering format.
An IBAN contains a two-letter country code, two check digits, and up to 30 characters for the Basic Bank Account Number, or BBAN, which encodes the bank, branch, and account number in whatever format that country uses domestically.
Originally built for transfers between EU countries, the standard has since spread well beyond Europe. Per the IBAN Register maintained with data licensed from S.W.I.F.T. SCRL (updated 8 May 2026), around 90 countries and territories now use the IBAN format, spanning most of Europe, parts of the Middle East and North Africa, and a growing number of Sub-Saharan African and Central Asian states.
The US, Canada, and Australia don't use IBANs for domestic transfers (Australia uses BSB codes instead), but their banks still process incoming IBAN-format payments from abroad without issue. Most Asian countries, Hong Kong and Singapore included, rely on SWIFT/BIC codes and local account numbers instead of IBANs for both domestic and cross-border transfers.
IBAN vs SWIFT/BIC Code: What’s The Difference?
An invoice from a European supplier will often list both an IBAN and a SWIFT/BIC code. They aren't interchangeable. They do two different jobs.
If you're transferring within IBAN countries (France to Germany, for example), you typically need both. The SWIFT/BIC code identifies the recipient's bank, and the IBAN identifies the specific account at that bank. For a full breakdown of how the SWIFT network routes a payment, see our guide to how SWIFT payments work.
If you're transferring to a non-IBAN country (France to the US, for example), you provide the SWIFT/BIC code plus the account and routing number, since the US doesn't use IBAN at all. Our IBAN vs SWIFT code comparison walks through this distinction in more detail, including which one to lead with on an invoice.
| Feature | IBAN | SWIFT/BIC Code |
|---|---|---|
| Purpose | Identifies a specific bank account | Identifies a specific bank or branch |
| Structure | Up to 34 characters: 2-letter country code, 2 check digits, up to 30-character BBAN | 8 or 11 characters: 4-letter bank code, 2-letter country code, 2-character location code, optional 3-character branch code |
| Origin | Introduced by the EU in the late 1990s | Created by SWIFT in the 1970s to replace telex instructions |
How IBAN Numbers Work
An IBAN packs four pieces of information into one string: the country the account sits in, a built-in error check, the bank and branch that holds it, and the specific account number. When a bank receives an IBAN, it validates the checksum before routing the payment, which is why correctly formatted IBAN transfers often clear in minutes rather than days.
A UK business receiving payment from a German client shows the difference in practice. With a correct IBAN, the sending bank verifies the format and routes the transfer directly. Without one, the same payment can require manual processing through several intermediary banks and take 3-5 business days to land.
That speed comes with a catch: the check digits confirm the IBAN is correctly formatted, but they don't confirm it belongs to the person you think it does. A valid IBAN that belongs to someone else is worse: outside the SEPA zone, the funds move and banks don't typically verify that the name matches the account before crediting it, so recovery is slow and isn't guaranteed. Within SEPA, banks must now flag a clear name mismatch before sending, though a close-enough match can still pass.
IBAN Format and Length by Country
Every IBAN has three parts: a 2-letter country code, 2 check digits, and the BBAN. Each country sets its own BBAN format and, as a result, its own total IBAN length, from 15 to 34 characters.
IBAN Length by Country:
- Germany: 22 characters
- France: 27 characters
- United Kingdom: 22 characters
- Spain: 24 characters
- Italy: 27 characters
- Netherlands: 18 characters
Enter the complete IBAN into the account number field. Most banking systems auto-format and validate it as you type, and the check digits are what makes that possible. They're a security feature, not filler.
Country-Specific IBAN Examples
Below are examples of what an IBAN looks like.
The French IBAN Number Format
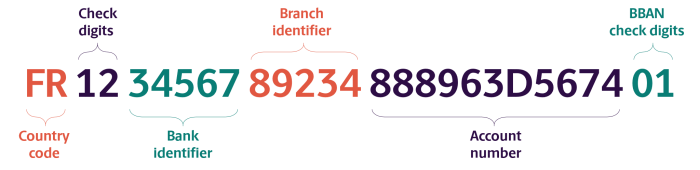
In this example, the country code 'FR' represents France, the IBAN check digits are 12, followed by five digits for the bank identifier (34567), five digits for the branch identifier (89234), 11 characters for the account number (888963D56774), and the last two digits (01) as the BBAN check digits.
The UK IBAN Number Format
In this example, the country code 'GB' represents the United Kingdom, the IBAN check digits are 18, followed by the four-character bank code (XXYZ), the six-digit sort code (123456), and the eight-digit account number (78901234).
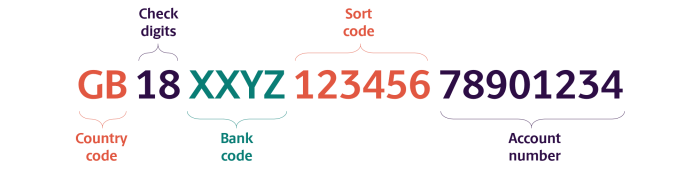
As mentioned, each country has its own BBAN format. Therefore, the length of the IBAN number varies from country to country. Although the UK IBAN number consists of 22 characters, it contains all the necessary details to ensure your international transfers arrive safely.
Why You Need an IBAN Number
You'll hit an IBAN requirement any time your business deals with a bank in an IBAN country. That most often means:
- Paying European suppliers, contractors, or service providers
- Receiving payments from clients based in IBAN countries
- Setting up recurring payments or direct debits with European partners
- Opening a business account with a bank in an IBAN country
- Processing refunds or reimbursements to European customers

How IBAN Transfers Work
To send money, you need the recipient's full name, address, IBAN, and bank details. For UK and EEA payments you'll also usually need their SWIFT/BIC code, and you may be asked what the payment is for and how you know the recipient. Our guide to telegraphic transfers covers how a traditional bank wire compares to online alternatives on cost and speed.
Traditional bank wires initiated at a branch tend to carry the highest fees. Online providers, including multi-currency business accounts, are usually cheaper for the same IBAN transfer.
On the receiving side, make sure the sender has your complete IBAN and, where relevant, your SWIFT/BIC code. Funds arriving in a foreign currency get converted at the prevailing exchange rate before they reach your account, so check what that rate is before assuming the number on the invoice is what you'll actually receive.
Using an IBAN for a US payment (which runs on routing numbers instead), or leaving one off a European payment that requires it, routes the transfer through extra intermediary banks. That typically adds 3-5 business days and USD 15-40 in additional fees. Check which format your recipient's country actually requires before you send.
Where to Find Your IBAN
| Method | How to Find It |
|---|---|
| Bank Statements | Check paper or electronic statements; usually near your account number and sort code. |
| Online Banking |
Step 1. Log in to your online banking account Step 2. Navigate to account details or account information Step 3. Look for "IBAN" or "International bank account number" Step 4. Copy the full alphanumeric code |
| Mobile Banking Apps | Open your app → Account details / International details / Payment details. |
| Bank Cards | Some banks (esp. in Europe) print the IBAN directly on debit/credit cards. |
| Contact Your Bank | Call customer service or visit a branch. |
| IBAN Calculators | Enter your country code, bank code, and account number. |
If your bank doesn't provide an IBAN at all, or you need IBANs across several countries, a foreign currency account built for multi-currency receipts can solve that gap directly.

Tip: Consider opening a virtual IBAN account if your local bank doesn't provide IBANs or you need IBANs for multiple countries.
IBAN Validation Best Practices
Validate before every international or telegraphic transfer. Even a single transposed digit can cause a significant delay.
If you only have part of a beneficiary's IBAN, an IBAN calculator can reconstruct the missing pieces from the country code, bank code, and account number. We have tested this tool multiple times and found it reliable in providing the correct IBAN.
Run a validation check on any IBAN that hasn't been used before, since beneficiaries don't always update their payment details on invoices or websites promptly. That single check catches most of the errors that would otherwise surface only after the payment fails.
What Happens if You Use the Wrong IBAN Number?
An incorrectly formatted IBAN gets rejected outright. Your bank will typically charge a fee to retrieve the funds, and the payment is delayed until that's resolved.
A validly formatted IBAN that simply belongs to someone else is the harder problem outside the SEPA zone, where banks generally don't verify that the recipient's name matches the account holder before crediting funds, so recovery can be slow and isn't guaranteed. Within SEPA, banks are now required to flag a clear name mismatch before the transfer completes, though a close match can still go through.

Important: If you suspect an incorrect IBAN was used, contact your bank immediately in order to make fund recovery easier.
Getting Paid Across Borders
Once you're dealing with suppliers or clients across several IBAN and non-IBAN countries, tracking which format each counterparty needs becomes its own admin task. A multi-currency business account that accepts both IBAN and SWIFT payments simplifies that decision: the same account can receive funds in either format, whichever the sender uses.
Statrys supports multi-currency receiving across 11+ currencies, global SWIFT connectivity, and FX rates from 0.1%, and is used by over 10,000 business account clients managing exactly this kind of cross-border payment mix.
FAQs
What is an IBAN number, and how does it work?
An IBAN (International Bank Account Number) is a standardised code that identifies your bank account internationally. It combines a country code, check digits, and your local bank details into one string of up to 34 characters, letting banks process cross-border transfers accurately without manual routing.
What are the main advantages of using an IBAN?
An IBAN (International Bank Account Number) is a standardised code that identifies your bank account internationally. It combines a country code, check digits, and your local bank details into one string of up to 34 characters, letting banks process cross-border transfers accurately without manual routing.
How do I find my IBAN number?
Check your bank statement, log into online or mobile banking, or contact your bank directly. It typically sits near your account number. European banks often print the IBAN on debit cards, and an IBAN calculator can reconstruct it if you only have your country code, bank code, and account number.
Is an IBAN the same as a SWIFT code?
No. Your IBAN identifies your specific account. A SWIFT or BIC code identifies your bank. For transfers into IBAN countries you typically need both: the IBAN tells the system which account to credit, and the SWIFT code tells it which bank to route the payment through first.
What happens if I use the wrong IBAN?
An invalid IBAN gets rejected, and you'll face delays and fees while it's corrected. A valid IBAN that belongs to someone else is worse: the funds move, and banks don't typically verify that the name matches the account before crediting it, so recovery is slow and isn't guaranteed. Report it to your bank immediately if this happens.
Share this content


